🚘 GST Applicability on Sale of Used Cars
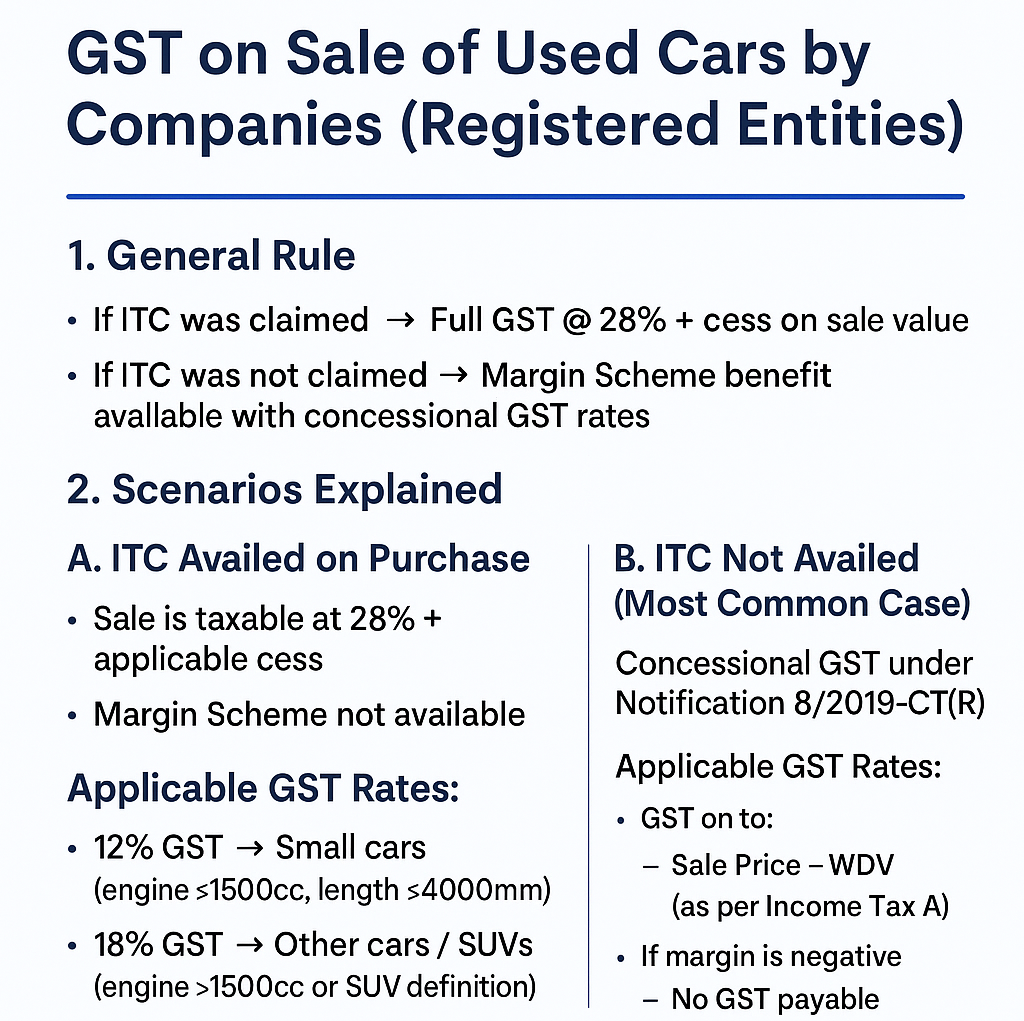
When a company sells its used car, GST treatment depends on whether Input Tax Credit (ITC) was claimed at the time of purchase.
If ITC was claimed → Full GST @ 28% + cess on sale value.
If ITC was not claimed → Margin Scheme benefit available with concessional GST rates.
—
📖 Legal Provisions
Section 7, CGST Act – Sale of motor vehicle is a supply.
Section 17(5), CGST Act – ITC on cars blocked (unless used for transport/training/sale).
Section 15, CGST Act – Valuation of supply.
Notification 1/2017-CT(R) – Regular GST rates (28% + cess).
Notification 8/2018-CT(R) – Concessional GST rates & Margin Scheme for old cars (when ITC not availed).
Notification 1/2017-CT(R) – Regular GST rates (28% + cess).
Notification 8/2018-CT(R) – Concessional GST rates & Margin Scheme for old cars (when ITC not availed).
Two Scenarios Explained
1. ITC Availed on Purchase
Sale is taxable at 28% + applicable cess.
Margin Scheme not available.
2. ITC Not Availed (Most Common Case)
Concessional GST under Notification 8/2018-CT(R).
Margin Scheme applicable.
✅ GST Rates (from 25.01.2018)
12% GST → Small cars (engine ≤1500cc, length ≤4000mm)
18% GST → Other cars / SUVs (engine >1500cc or SUV definition)
✅ Valuation (Margin Scheme)
GST on: Sale Price – WDV (as per Income Tax Act)
If margin is negative → No GST payable
Example Calculation
Car purchased in 2020 for ₹10,00,000 (no ITC claimed)
WDV (as on Aug 2025) = ₹2,00,000
Sale Price = ₹3,00,000
👉 Margin = ₹1,00,000 (3,00,000 – 2,00,000)
👉 GST @ 18% = ₹18,000
If sold at ₹1,50,000 → Margin = –₹50,000 → No GST payable
Frequently Asked Questions
Q1. Is GST applicable on sale of used cars by companies?
Yes. GST is applicable if the seller is a registered entity.
Q2. What if ITC was not claimed?
Concessional GST rates (12% / 18%) under the Margin Scheme apply.
Q3. What if the margin is negative?
No GST is payable when sale price < WDV.
Q4. Do individuals selling personal cars pay GST?
No. GST applies only to sales by registered persons in course of business.
—
⚠️ Disclaimer
This article is for informational purposes only and should not be treated as professional tax or legal advice. Please consult a qualified tax professional for guidance specific to your business.